


Build. Test. Improve Your Trading Algorithms.
An integrated development environment for researching, coding, backtesting, and evaluating algorithmic strategies.
An integrated development environment for researching, coding, backtesting, and evaluating algorithmic strategies.
Strategy research usually spreads across spreadsheets, notebooks, scripts and screenshots. Quantzivo Studio is designed to keep it in one place: define rules, write code, run backtests with explicit assumptions, and review the results side by side.

Product status: Quantzivo Studio is in development. Features described here reflect the planned scope and may change before release.
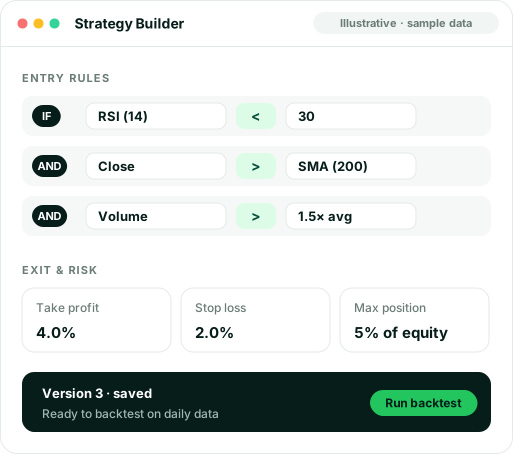
Each module is designed to work on its own and to hand its output to the next step without copying files around.

Compose entry, exit and risk rules from technical conditions without writing code.
Learn more

Write strategies in Python with templates, a clear structure and research notebooks.
Learn more
Simulate strategies on historical data with configurable costs, slippage and fill timing.
Learn more
Equity curves, trade lists, benchmark comparisons and period breakdowns for every run.
Learn more
Drawdowns, volatility and risk-adjusted ratios, shown alongside the assumptions behind them.
Learn more
Run strategies forward on virtual portfolios with simulated orders. No broker, no real money.
Learn more
Planned documentation, Python examples, code templates and integration guides.
Learn more
Explore data and prototype signals before promoting an idea into a full strategy.
Learn moreStudio is organized around a disciplined research loop. Most ideas fail somewhere along it, and finding that out early is the point.

Write down the market behavior you expect and why it might persist. A clear hypothesis is easier to reject.
Translate the idea into explicit entry, exit and risk rules in the Strategy Builder.
Strategy Builder
Extend or replace visual rules with Python when the logic needs more flexibility.
Algo developmentSimulate the strategy on historical data with costs, slippage and realistic fill timing switched on.
Backtesting
Check drawdowns, risk-adjusted metrics, out-of-sample periods and sensitivity to parameters.
Metrics explainedObserve the strategy on new data in a simulated portfolio and compare it with the backtest.
Paper trading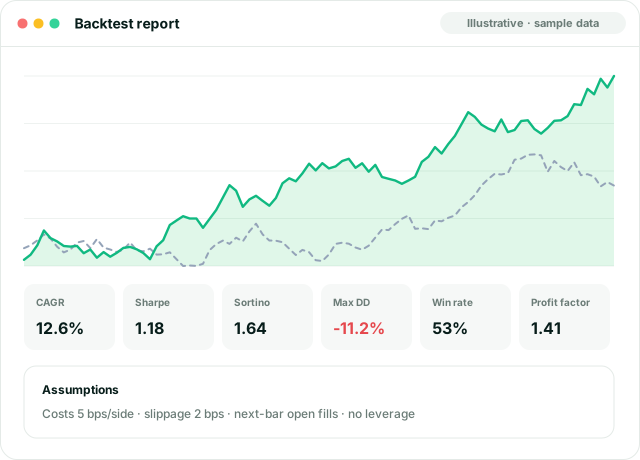
A return number on its own says little. Studio reports are designed to print the costs, slippage, fill model and data range next to every metric, so a result can be questioned and reproduced.
 Equity curve, drawdown chart and full trade listRisk-adjusted metrics compared with a benchmarkSide-by-side comparison of strategy versions

Backtested and paper-traded results are hypothetical. They do not account for every real-world factor and do not indicate future performance.
Studio is designed for research and learning. It suits anyone who wants to turn ideas into testable rules and understand the results honestly.

Apply what you learn about markets and Python to strategies you can actually run and inspect.

Work in Python with a defined strategy structure instead of rebuilding a backtester from scratch.

Turn discretionary rules of thumb into explicit conditions and see how they held up historically.

Run walk-forward tests, compare versions and keep a log of every experiment.

Prototype systematic ideas and communicate them with clear, assumption-aware reports.

Demonstrate backtesting pitfalls and risk concepts with strategies students can modify themselves.
Learn the concepts, build and test with them, then research the market context. Each platform is designed to hand off naturally to the next.
Courses cover the Python, indicators, backtesting methods and risk concepts that Studio puts into practice.

Turn lessons into working strategies, test them with explicit assumptions and track every version.

Use AI-assisted research to understand the technical, fundamental, news and macro backdrop behind a strategy's results.
Studio is a place to build and evaluate strategies. It is not a brokerage, and it does not place orders with real money.
| Capability | In Studio's planned scope | Notes |
|---|---|---|
| Rule-based strategy building | Planned | Visual entry, exit and risk rules with versioning |
| Python strategy coding | Planned | Templates, notebooks and a defined strategy structure |
| Historical backtesting | Planned | Configurable costs, slippage and fill timing; results are hypothetical |
| Paper trading | Planned | Simulated orders on virtual portfolios only |
| Live brokerage execution | - | Not offered. Studio does not connect to brokers or route real orders. |
| Buy or sell recommendations | - | Not offered. Studio provides tools for your own research, not investment advice. |
What the Studio is designed to do, what it will not do, and how to follow its progress.
Request early access to hear about previews, share the workflows you need, and see the Studio as it takes shape.